How do I check wildfire insurance before closing on a Summit County home?
Get Summit County wildfire insurance quotes in the first days of your contract, well ahead of your insurance deadline. The quote can change what the house is worth to you.
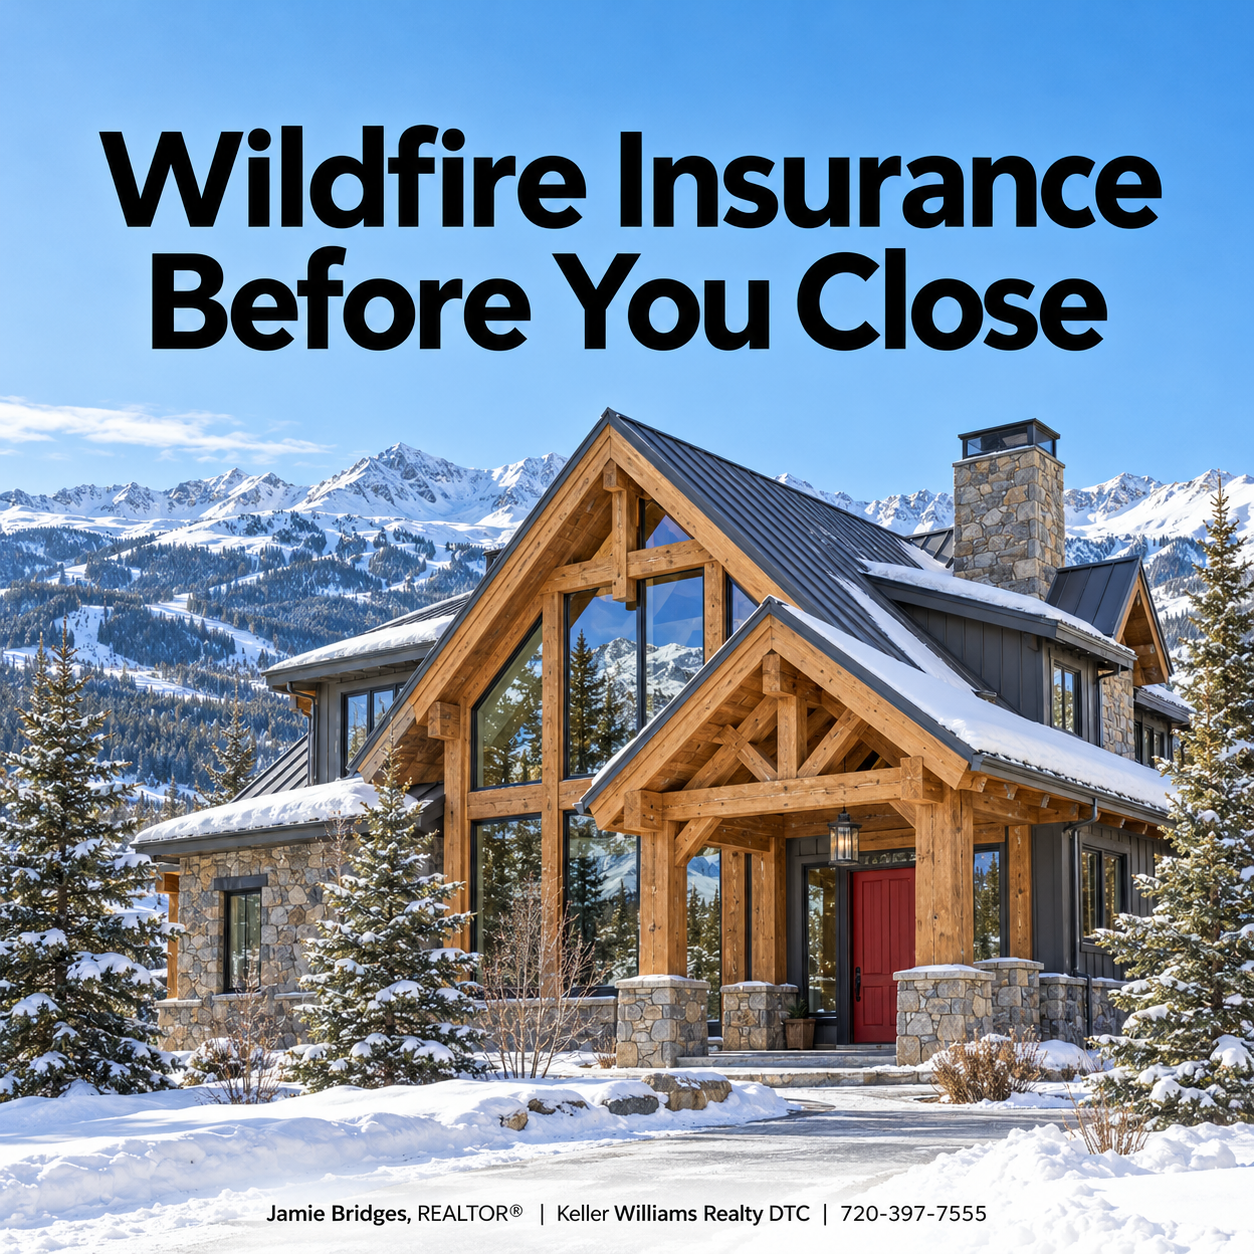
It’s early November in Frisco. There’s fresh snow on the roof of the house you just put under contract, and wildfire feels like next summer’s problem. Your insurer doesn’t see it that way. Since July 1, 2026, Colorado law requires insurers that use a wildfire risk score to give you that score and let you appeal it. That score doesn’t melt with the snow.
For example, say you’re buying a $1.4 million timber-frame home in the trees above Breckenridge, and two standard carriers decline it. Colorado’s FAIR Plan, the state’s insurer of last resort, caps a homeowners policy at $750,000 and pays actual cash value. You’d want to find that gap on Day 5 of your contract. Once your deadline passes, the gap is yours.
This post shows what to check, and in what order, so the insurance answer lands inside your contract deadlines.
Wildfire Risk in Summit County Doesn’t Take the Winter Off
Summit Fire & EMS frames the local fire season as roughly April 1 to November 1. Its spring 2026 wildfire presentations followed what it called a record warm and record dry winter. The district also notes that nearly 80% of the county’s land is U.S. Forest Service land, from the hills above Silverthorne to the slopes around Keystone.
Insurers price that exposure the day you bind the policy, whatever the weather. A policy you buy in December is the one in force next August. Treat the snow in your listing photos as scenery.
Your Contract’s Property Insurance Termination Deadline
The Colorado Real Estate Commission’s Contract to Buy and Sell Real Estate (Residential), for use on or after January 1, 2026, covers this in Section 10.5, Insurability. You can terminate on or before the Property Insurance Termination Deadline if you’re unhappy with the availability, terms and conditions, or premium of property insurance on the home. It’s your sole subjective discretion.
The date itself sits in the Section 3 deadline table, and it’s negotiated like every other date. In a quick mountain deal, it can arrive fast. Call for quotes the day your contract is signed. A quote request that waits for the inspection report can run out of room.
If the home has an older roof, the same timing problem shows up in Denver too. Jamie’s post on buying a home with an older roof in Colorado walks through how roof age affects quotes.
What to Check Before Your Deadline
Look Up the Property’s Wildfire Risk
The Colorado State Forest Service publishes the Colorado Wildfire Risk Public Viewer, a free map that shows potential wildfire intensity and burn probability near any location you choose. It also shows past large fire perimeters and Community Wildfire Protection Plan boundaries. Look up the address before you write your offer. It gives you a rough read on what an underwriter will see.
Ask for the Wildfire Risk Score
HB25-1182, signed May 28, 2025, took effect July 1, 2026. Insurers that use a wildfire risk model or score to underwrite, price, or surcharge must give applicants and policyholders an annual written notice with the score and any discounts that apply. You can appeal a score directly to the insurer. If a quote comes back high, ask for the score and the reasons behind it.
Ask the Seller for a Claims History Report
Insurers look at the home’s past claims, often through what’s called a CLUE report. The current owner is the one who can order it. The Colorado Division of Insurance notes that Colorado law allows one free consumer report per year. Ask the seller for one early in due diligence, and read it next to the Seller’s Property Disclosure.
Ask About the Roof and Defensible Space
Summit Fire & EMS says Class A roofs have been required in the county for more than 30 years. Ask the seller for the roof’s age, material, and any permits. Your insurance agent will want those details for the quote.
Then walk the lot with the three defensible space zones in mind: 0 to 5 feet, 5 to 30 feet, and 30 to 100 feet from the house. Ask whether the seller has done any mitigation. Summit County runs a free chipping program; in 2026, pickup ran July 20 to 24. After you close, Summit Fire & EMS offers a free courtesy home wildfire assessment for existing homes.
Know What the Wildfire Resiliency Code Means for Future Work
Summit County adopted the 2025 Colorado Wildfire Resiliency Code on March 24, 2026. On May 19, 2026, the Town of Dillon adopted it as adopted by the county and Summit Fire & EMS, and consented to their enforcing it in town. Keystone adopted it by its own ordinance, effective June 30, 2026.
The code doesn’t force a retrofit on an existing house. It kicks in when you do work. Replacing 25% or more of the roof or exterior walls generally means the whole replacement meets the code. An addition of 500 square feet or more must meet new-construction rules. Ask your insurance agent how your policy handles code upgrade costs on a rebuild.
When Standard Carriers Say No: The Colorado FAIR Plan
The FAIR Plan was created by HB23-1288, signed May 12, 2023. The bill caps residential property coverage at $750,000. The Colorado Division of Real Estate’s advisory says that figure covers property and contents combined, on an actual cash value basis. Covered perils include fire, lightning, windstorm, hail, and smoke.
Eligibility is narrow. The advisory describes three declinations from standard insurers, an inspection, and underwriting that can still deny the application. Applications go through an approved agent. On a higher-priced Summit County home, the cap may leave a gap your agent would need to fill another way.
The state is working on costs from other angles. SB26-155, signed June 4, 2026, creates the Strengthen Colorado Homes Enterprise. Starting in 2027, it funds grants for hail- and wind-resistant roofs, with priority to primary residences. It also orders a study of insurance in high wildfire risk areas.
Build the Insurance Check Into Your Offer
Jamie Bridges, a REALTOR® with Keller Williams Realty DTC, works with second-home and primary-home buyers in Breckenridge, Frisco, Silverthorne, Dillon, and Keystone. He holds the Resort and Second-Home Property Specialist (RSPS) designation. Before an offer goes in, he asks the listing side for the roof age and any claims history. Then he sets the Property Insurance Termination Deadline with enough room to get quotes back on a second home before the date arrives.
Buying a condo or townhome changes the picture. The HOA’s master policy carries much of the building risk, and a gap there can turn into a special assessment on your Summit County condo. Ask for the association’s insurance summary with your HOA documents.
Coverage details depend on the home and the policy, so talk with a licensed insurance agent before your deadline.
Frequently Asked Questions
Does the Colorado FAIR Plan pay full replacement cost? No. The Division of Real Estate’s advisory says FAIR Plan homeowners coverage pays actual cash value, up to $750,000 for property and contents combined. On a higher-priced Summit County home, that can fall short of the cost to rebuild.
Is wildfire risk lower in Summit County in the winter? Summit Fire & EMS frames the active season as roughly April 1 to November 1, but insurers underwrite the full year the policy covers. Spring 2026 followed a record warm and record dry winter, so snow on the ground today tells you little about next summer.
Can I cancel my contract if the insurance quote is too high? Under Section 10.5 of the 2026 Colorado contract, you can terminate on or before your Property Insurance Termination Deadline if the availability, terms, or premium don’t work for you. After that date passes, that right is gone.
If you’re shopping for a mountain home this winter, run the insurance check before you fall for the view. Jamie Bridges is a REALTOR® with Keller Williams Realty DTC serving the Denver Metro Area and Summit County, Colorado. Call or text Jamie at 720-397-7555 to talk about your next move.
Sources: Colorado Real Estate Commission, Contract to Buy and Sell Real Estate (Residential), for use on or after January 1, 2026, Sections 3 and 10.5, via the Colorado Division of Real Estate, accessed October 30, 2026; Colorado Division of Real Estate, HOA Center Advisory on the FAIR Plan, February 13, 2025; Colorado General Assembly, HB23-1288 (signed May 12, 2023), HB25-1182 (signed May 28, 2025, effective July 1, 2026), and SB26-155 (signed June 4, 2026), leg.colorado.gov, accessed October 30, 2026; Colorado Division of Insurance, Homeowners and HOA Insurance Toolkit, accessed October 30, 2026; Colorado State Forest Service, Colorado Wildfire Risk Public Viewer, via the Colorado Energy Office, accessed October 30, 2026; Summit Fire & EMS, Wildfire Preparation 2026 and Courtesy Home Wildfire Assessment pages, accessed October 30, 2026; Summit County 2026 chipping program notice via Buffalo Mountain Metropolitan District, accessed October 30, 2026; Town of Dillon Resolution No. 27-26, Series of 2026, May 19, 2026; Town of Keystone Ordinance No. 2026-O-04, effective June 30, 2026; Colorado Division of Fire Prevention and Control, 2025 Colorado Wildfire Resiliency Code, accessed October 30, 2026. Data deemed reliable but not guaranteed. General information only. This isn’t legal or insurance advice; talk with a licensed insurance agent and, for contract questions, a real estate attorney.